The U.S. House Ways and Means Committee is set to evaluate a new piece of legislation on Wednesday aimed at reinstating a full federal tax deduction for gambling losses against winnings.
This proposed legislation seeks to remove the existing 90% cap on deductions for wagering losses, applying to taxable years starting after December 31, 2025, and offering retroactive relief for the year 2026.
The gambling-related provision has been incorporated into House Resolution 10357, known as the Digital Asset Tax Certainty Act, which includes a comprehensive 98-page legislative package. Additionally, the committee is reviewing other proposals concerning digital assets, healthcare, and tax regulations.
This provision is derived from the bipartisan FULL HOUSE Act, which stands for Facilitating Useful Loss Limitations to Help Our Unique Service Economy, introduced in January by Representative Max Miller (R-Ohio). The bill has garnered support from four Democrats and two Republicans, including Nevada's Representatives Steven Horsford and Susie Lee.
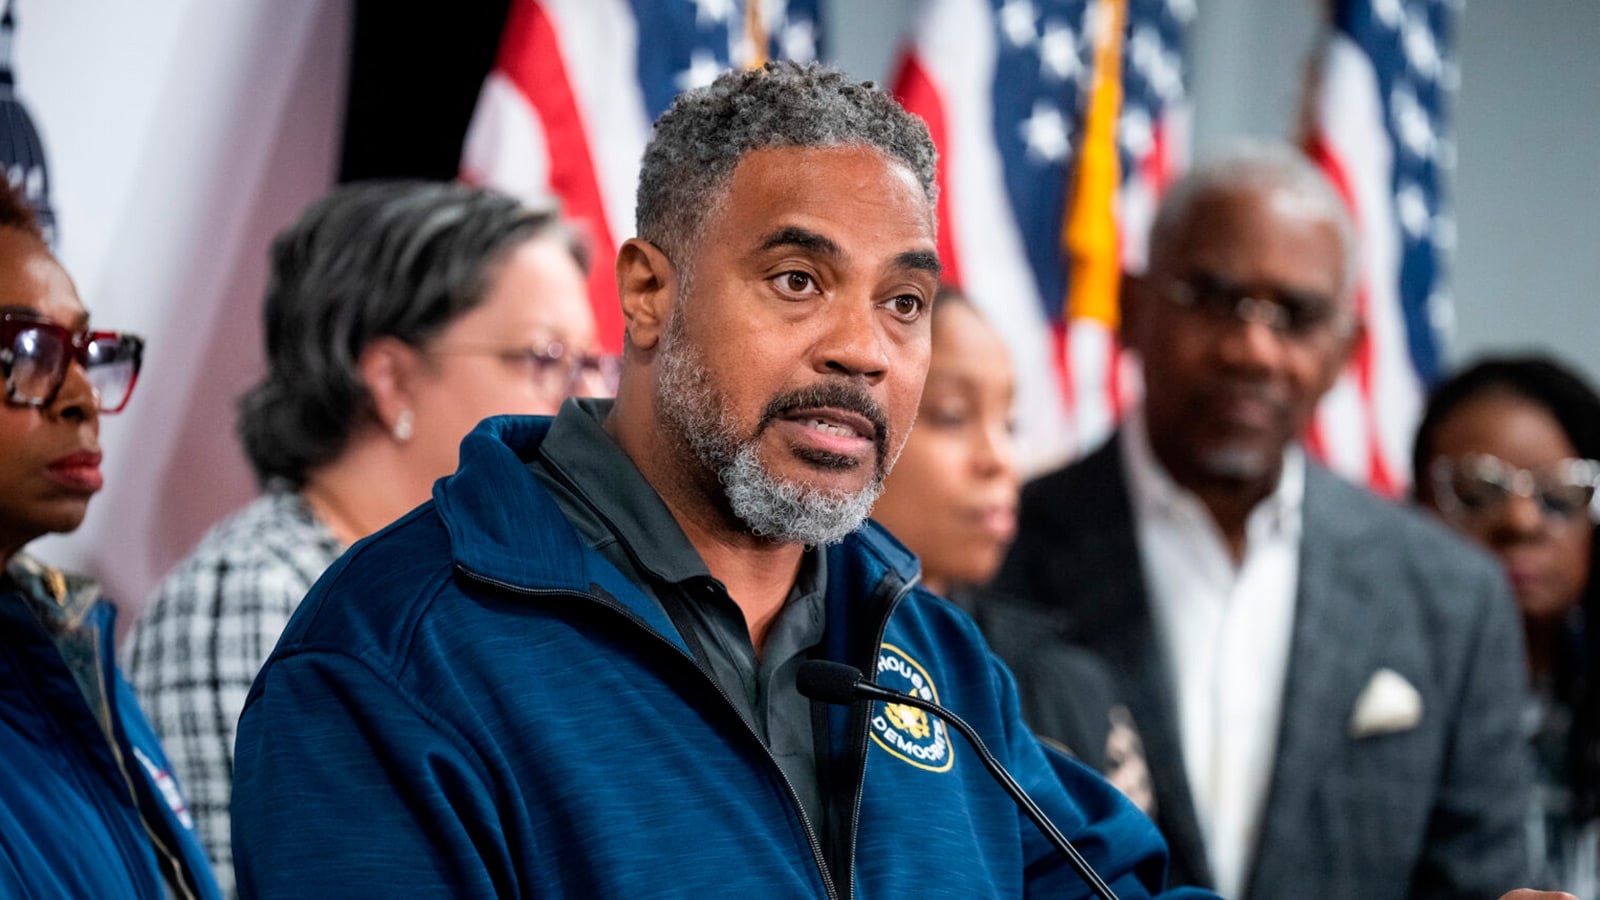
“No one should be taxed on money they haven't actually earned. This is why I proposed the bipartisan FULL HOUSE Act and have dedicated months to advocating for the complete repeal of the unjust gambling tax imposed by Senate Republicans last year,” stated Horsford.
He emphasized the importance of this initiative for Nevada, noting, “It’s crucial for our economy and for the workers and small businesses reliant on tourism and gaming. Their livelihoods are on the line.”
Representative Dina Titus, who has been a proponent of the similar FAIR BET Act, also expressed her support for the new provision. “I’m thrilled that my proposal for a gambling loss tax deduction has finally found its way into a tax package,” Titus remarked. “I urge my colleagues on the Ways and Means Committee to expedite its passage this week.”
Prediction markets have indicated over $3.1 million in trades regarding the likelihood of the deduction being reinstated, with traders estimating a 48% chance that the 90% limitation will be abolished by April 1, 2027.
The legislative text clarifies, “The proposal removes the 90% limitation on the deduction for losses incurred from wagering transactions.” It further states, “Thus, for taxable years commencing after December 31, 2025, losses incurred during the taxable year from wagering transactions can be deducted to the full extent of the gains from such transactions during that year.”